

Every so often I like to run a good, old-fashioned deep dive—pick a question, run a few tests, and see what the data actually says. This week’s experiment produced a surprising result: a tiny insurance ETF kept beating everything else I threw at it.
This week’s quest starts with Risk Parity Radio, where Frank often talks about a fund I hadn’t paid much attention to before:
Invesco KBW Property & Casualty Insurance ETF (KBWP)
After hearing about it in multiple episodes (such as #473, #429 and #427, and perhaps most thoroughly in #293), it caught my ear as a possibility for the long-sought after but rarely seen unicorn in DIY investing: something that has equity-like returns but diversifies like something totally different.
Intrigued after hearing so much, I decided to put KBWP through its paces and investigate three things:
How it performs on its own
How it compares to other lower-Beta equity funds
How it can improve a diversified portfolio
What Exactly Is KBWP?
KBWP is a fairly narrow ETF (just 26 holdings) consisting of property and casualty insurance companies. Top holdings include:
These firms specialize in property and liability insurance, not life insurance or annuities, and thus represent a sub-sector of the insurance industry.
Property and casualty insurers operate on short policy cycles. If risk rises, they can raise premiums relatively quickly. As long as premiums exceed claims, the business works.
And demand for insurance tends to be sticky. Even in recessions, people cut vacations long before they cancel their homeowner’s policy.
That distinction matters, and may explain why the sector behaves a little differently from the rest of the stock market.
KBWP is also firmly on the value side of equities, with an average P/E ratio under 12, and a P/B ratio just a hair over 2. That’s another reason it might follow a different path than the growth-dominated S&P 500.
One drawback of KBWP is a relatively high expense ratio of .35%. In these days of no-fee trading, that’s a bit high for a fund that you could replicate yourself.
Indeed, Frank does exactly that – he just invests directly into the funds that KBWP holds. This is not too difficult, since 41% of assets are in the top five companies and 61% in the top ten.
The Bigger Idea: Low-Beta Equities
The real appeal of KBWP is the possibility that it might be an equity-like return source that behaves differently from other equities, or more technically, low-Beta equities — stocks that move less closely with the broader market.
“Low” is doing a lot of work here, since it’s just chasing rainbows to think you’ll ever find a perfect example. For something that had equity-like returns, we’d be happy with 0.6, and over the moon if we could get to 0.5 (remember, lower is better for diversification benefits). For comparison, since 2001:
Gold and managed futures: correlations to SPY near 0
Long-term Treasuries: about -0.3
Typical equities: 0.8–1.0, meaning they move very closely with the S&P 500.
So, let’s be realistic: low-beta equities are not separate asset classes. They’re just slightly different flavors of equity risk.
But sometimes that difference is enough to improve a portfolio.
The Competitors
To see how KBWP stacks up, I compared it against five other “low-Beta equity” candidates.
1. Small-Cap Value: Vanguard S&P Small‑Cap 600 Value ETF (VIOV)
KBWP itself looks very value-like, so I decided to test it against VIOV, which has a P/E at 14.8 and a P/B of 1.3.
2. Real Estate: Vanguard Real Estate ETF (VNQ)
REITs are often mentioned as equities that behave somewhat idiosyncratically, so this seemed perfect to include. I’ve long been skeptical and on record as saying that investing in REITs is ultimately not really necessary, so let’s see how it compares.
3. Preferred Shares: iShares Preferred and Income Securities ETF (PFF)
Preferred shares are a hybrid of stocks and bonds and often carry a beta around 0.5. They are definitely unique, but let’s see if that translates to a good investment.
4. Consumer Staples: State Street Consumer Staples Select Sector SPDR Fund (XLP)
Think durable businesses like Walmart, Costco and Coca-Cola, economic stalwarts with low P/E ratios and whose revenues stay steady through economic cycles.
5. Utilities: State Street Utilities Select Sector SPDR Fund (XLU)
Highly regulated, stable companies that historically behave differently from the broader market. By the way, in my old blog, XLU was the “winner” when I did a similar test of low-Beta equities, beating out XLP by just a hair.
Test 1: How’d They Do?
KBWP launched in December 2010, giving us about 15 years of data — not ideal, but workable. I tested KBWP along with the other five, plus SPY for reference.
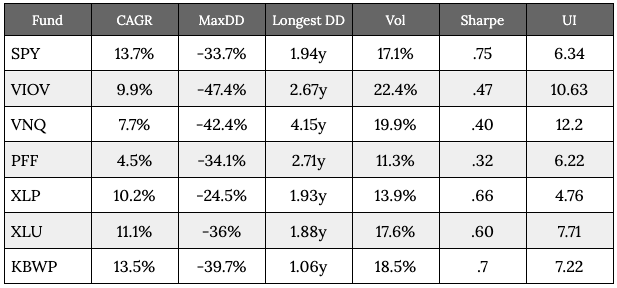
The headline result: KBWP looks excellent. It delivered:
A CAGR nearly identical to the S&P 500
Much higher returns than the other low-Beta funds
Middle-of-the-pack volatility
The shortest maximum drawdown duration, even though its maximum drawdown was towards the higher end
Even more interesting was the correlation data. I added in other signature funds from other asset classes such as TLT, GLD and DBMF, and this is where I started to suspect KBWP might be something special.
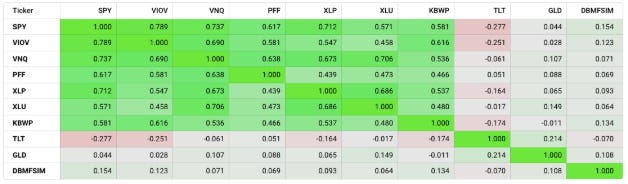
KBWP’s correlation with the S&P 500 came in around 0.58, one of the lowest in the group. Comparing KBWP to the other basic building blocks of a portfolio again shows consistently good numbers. In this regard, XLU and XLP also did well.
A correlation of .58 suggests it may not be a unicorn, but still, that is a number low enough to have a positive effect on portfolio resilience, stability and its perpetual withdrawal rate.
Test 2: How Did These Funds Behave in Crashes?
The last decade has been a strong bull market, so I wanted to see how these funds did when things didn’t go so swimmingly. In my follow-up, I backtested three difficult periods:
The perfect storm of bad news in the Q4 2018 selloff
The lightning-fast COVID crash (February 20–March 23, 2020)
The long, slow grind of 2022, when we paid for the excesses of 2021
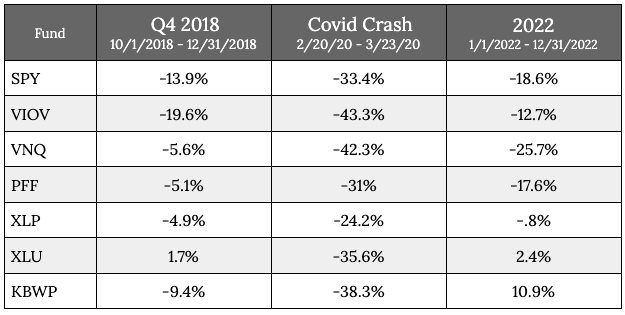
XLU was best in the first, XLP the least bad in the second, but the standout result is KBWP’s performance in 2022.
While just about everything was getting crushed, KBWP returned almost 11% – a remarkable outcome.
Test 3: Maybe It Is Just 2022?
One obvious question: is KBWP’s overall strong record just a fluke driven by that one remarkable year of 2022?
To test that, I removed 2022 entirely and ran the performance across the remaining years (the backtest is in two parts: the first four funds and then SPY plus the last three).
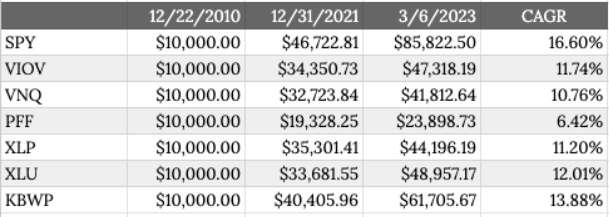
Even without that year, KBWP still came out on top, with a 13.9% CAGR — beating second-place utilities by nearly 2 percentage points.
So its performance advantage doesn’t appear to be a one-year anomaly.
Test 4: What About Inside a Portfolio?
The most important test, though, is portfolio impact.
After all, I’m not just holding these funds without context; it’s all about how their addition can improve both returns and resilience.
To measure that, I modified a Golden Butterfly portfolio by adding each candidate as a sixth equally weighted asset. Again, the backtest is divided into parts 1 and 2.
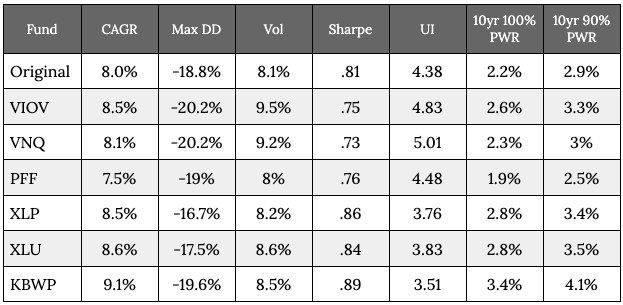
KBWP won again.
It delivered:
The highest CAGR
The highest Sharpe ratio
The lowest Ulcer Index
The best perpetual withdrawal rates
It was such a clean sweep that I reran the test just to check for errors.
Nope. KBWP really was that strong.
What Didn’t Work
Some funds simply didn’t add much.
Preferred shares were just a flop. They didn’t provide enough return or diversification to matter.
And once again, my skepticism about REITs remains intact. When I started my investing journey, I truly wanted to like REITs as an asset class, but reality has kept getting in the way. As these tests show, VNQ has produced mediocre returns and correlations that weren’t particularly helpful.
What Was Fine
On the other hand, both Utilities Select Sector SPDR Fund and Consumer Staples Select Sector SPDR Fund held up well.
They don’t get as much attention as REITs, but historically they’ve provided much of the defensive behavior investors hope REITs will deliver.
Small-cap value, meanwhile, acquitted itself well. KBWP proved better in basically all the tests I did in comparison to VIOV, but they were close. To me, this suggests that we may just want to think of KBWP as a really great value fund.
VIOV is not even my favorite in the space (that would be AVUV, though I don’t have a write-up about it yet on this Substack), so perhaps AVUV would be competitive with KBWP. The backtest there wouldn’t be very long (under seven years), so we may not have a definitive answer there for some time.
What Was Great
After running these tests, my takeaway is this:
KBWP may not be a mysterious “new asset class,” but it still has a lot to offer.
It looks to be a very good value fund built on an unusually resilient business model, and one that investors should definitely consider.
Insurance companies generate steady cash flows, adjust pricing quickly, and operate in a sector that doesn’t depend heavily on economic growth.
That combination appears to produce equity-like returns with a somewhat different path to achieving them, and that’s a great addition to a portfolio.
One Big Caveat
There is one long-term concern.
Insurance ultimately depends on the ability to price risk correctly. In a world of increasing climate-related disasters, I sometimes wonder whether insurers will always be able to keep up.
In places like Florida, homeowner insurance costs are already rising dramatically, and at some point, the scale of destruction may lead to premiums so high that people may just choose to self-insure.
I’m not predicting that outcome — no crystal balls here – but it’s something worth keeping in mind. If there were one business I think I wouldn’t want to be in when the world immolates, it would be property insurance.
Final Verdict
Despite that caveat, the data here is clear:
The Invesco KBW Property & Casualty Insurance ETF performed extremely well across every test. It offers:
Strong returns
Lower correlation to equities than most other equity funds
Measurable improvements inside diversified portfolios
It doesn’t replace small-cap value. The academic support for value as a factor is just too strong to ignore, though it would be perfectly reasonable for an investor who wanted to invest in KBWP as part of a value strategy.
But it absolutely deserves consideration alongside value strategies in the equity sleeve of a diversified portfolio.
And based on these results, I have to admit: Frank might be onto something!
Great article Justin and I have already incorporated a slice of KBWP into my portfolio as a result. There is one aspect of your last test incorporating KBWP into the Golden Butterfly that I didn’t quite understand however. Since the GB Portfolio already contains a 20% slice of small cap value, adding more SCV as a sixth equally weighted asset class doesn’t seem like it would result in a fair comparison of SCV against the other low beta equities that weren’t already represented in the base model portfolio. Naturally, adding more of an existing asset class to a portfolio isn’t going to have the same desired impact in terms of diversification and lack of correlation benefits as adding a novel asset class to that portfolio.
In order to produce a fair comparison of SCV against KBWP, it seems that you’d need to start with a model portfolio that doesn’t already have an allocation to SCV. This may not be so straightforward however, since most if not all established Risk Parity Portfolios with respectable high withdrawal rate metrics are going to have an existing allocation to SCV.